

Reword all the content from original article, keep HTML tags, make it SEO friendly and unique
With few exceptions, it’s been a tale of woe in 2026 for casino stocks, but investors scouring the landscape for rebound candidates may want to focus on a simple metric: efficiency.
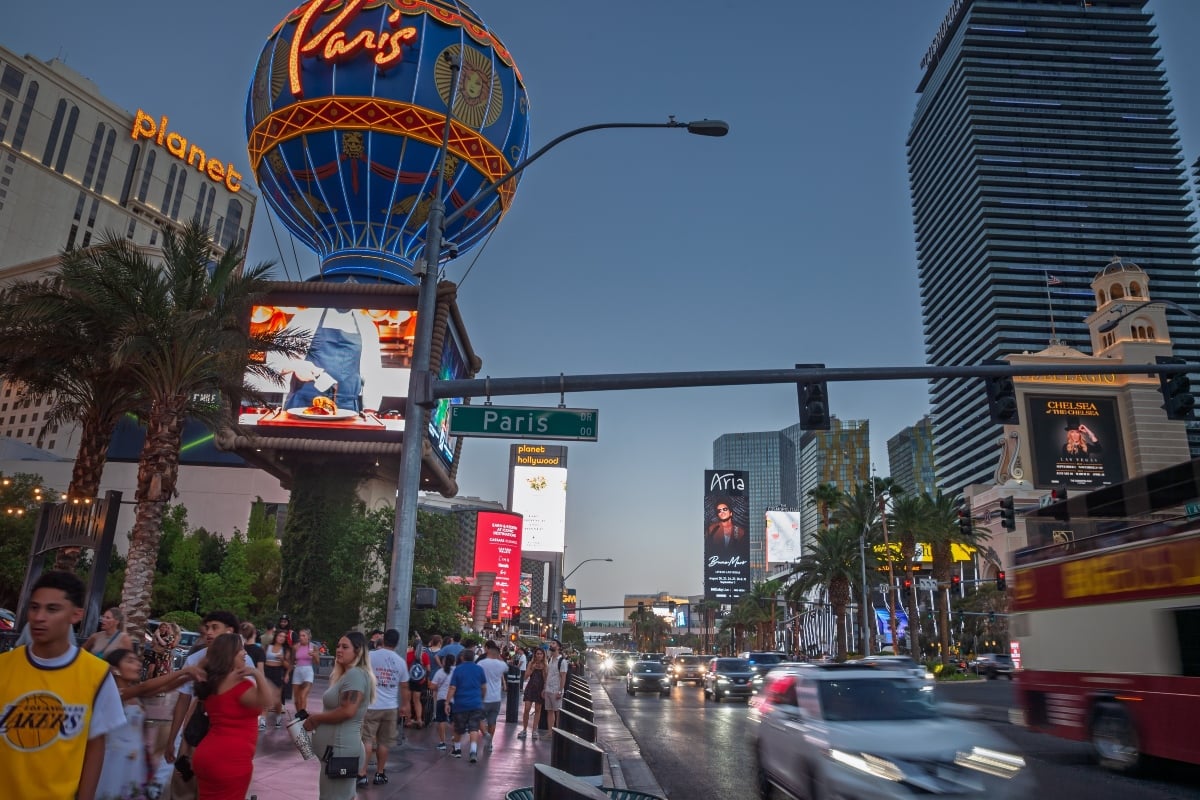
Noting that “quality over quantity” matters and that operators dedicated to premium strategies “can justify premium valuations,” Jefferies analyst David Katz highlights the Las Vegas Strip as a prime example of a gaming jurisdiction where efficiency reigns. He argues the primary U.S. casino hub is now more of “a hospitality and entertainment business supported by gaming rather than a pure casino model.”
Accounting for that shift, Wynn Resorts (NASDAQ: WYNN) stands out due to its well-documented focus on high-end clientele. Katz projects Wynn will generate $180,000 in earnings before interest, taxes, depreciation, and amortization (EBITDA) per Las Vegas room this year. That comfortably outperforms the estimated per-room EBITDA of $83,000 for Caesars Entertainment (NASDAQ: CZR) and $77,000 for MGM Resorts International (NYSE: MGM).
MGM and Caesars are the two largest Strip operators with significantly more room stock than Wynn, but the Encore operator generates greater per room earnings than its two rivals.
Efficiency Matters With Regional Casino Stocks, Too
The themes of efficiency and quality as drivers of potential casino stock upside extend beyond the Las Vegas Strip. Those metrics are relevant with regional casino names, too, and as Katz points out, Monarch Casino & Resort (NASDAQ: MCRI) and Red Rock Resorts (NASDAQ: RRR) score well on those metrics.
The analyst highlights Monarch’s two-casino model and Red Rock’s dedication to the Las Vegas locals market as favorable traits.
Operators with concentrated exposure to favorable local markets continue to generate higher returns than those operating broad portfolios across competitive jurisdictions,” writes Katz. “Our analysis suggests local market share, database quality, and disciplined capital deployment are more important drivers of earnings density than scale alone.”
There’s ample talk that Monarch could be a buyer of gaming assets that are on the market or some that will soon come up for sale, but the company is highly selective. It’s been rewarded for that approach because it’s one of this year’s best-performing casino stocks despite owning just two gaming venues.
Quality Over Quantity
While sprawling national portfolios offer geographic diversification, investors in 2026 are demanding operational efficiency over sheer scale.
“Operators generating the highest EBITDA per gaming position or EBITDA per room tend to benefit from differentiated assets, premium customer exposure, attractive market positions, and disciplined capital deployment,” adds Katz. “Ultimately, we believe future share performance is likely to be driven less by footprint expansion and more by management teams’ ability to increase earnings generated from existing rooms and gaming positions.”